The Big Story
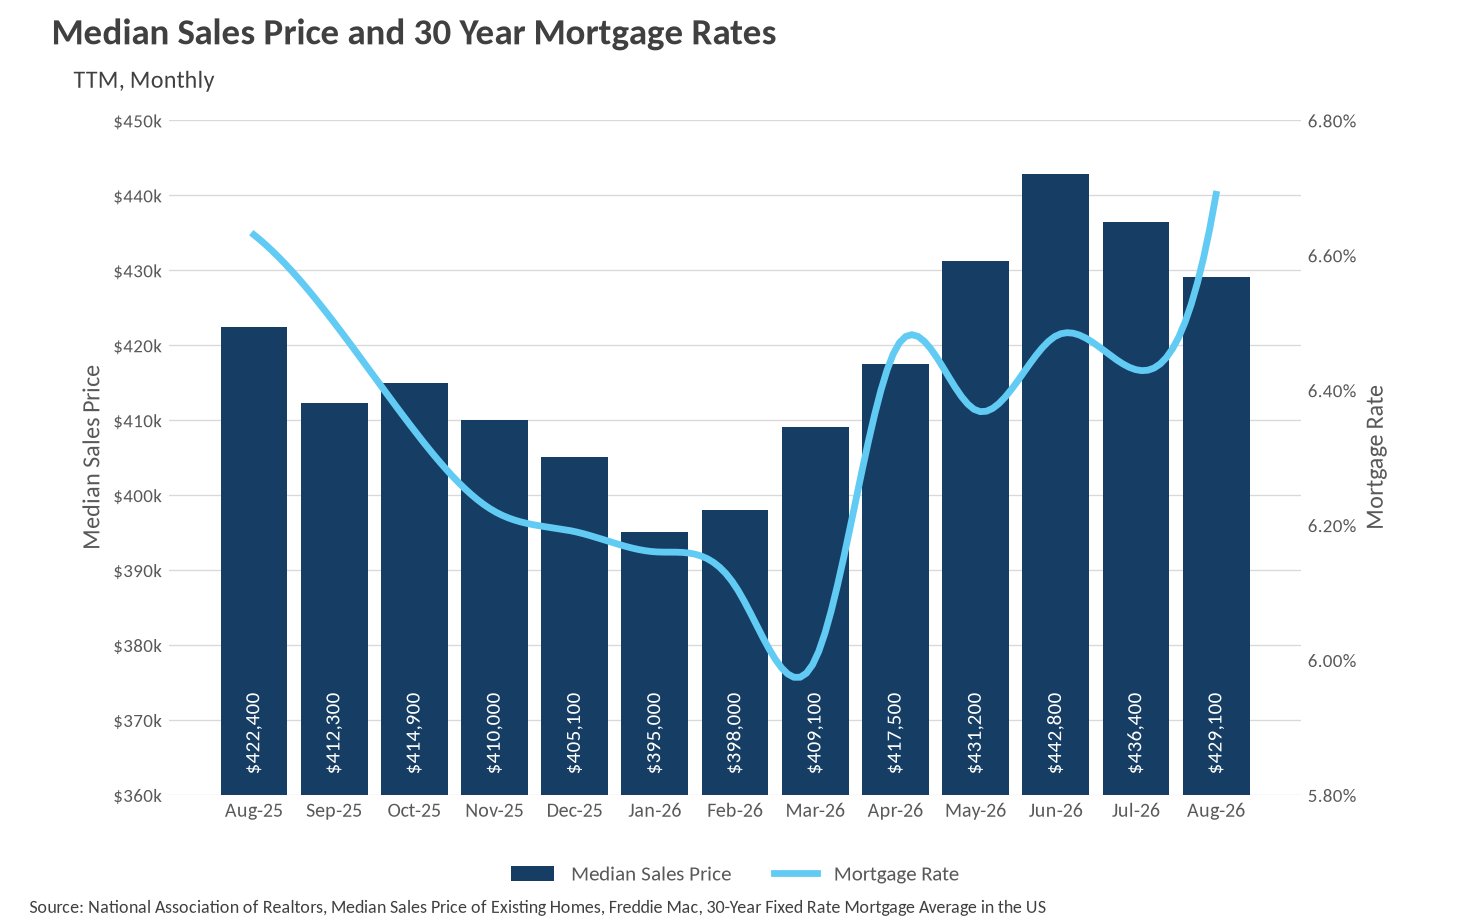
- Median home sale prices slipped for the second straight month in August, falling to $429,100 from June's peak of $442,800, though they remain slightly above where they were a year ago.
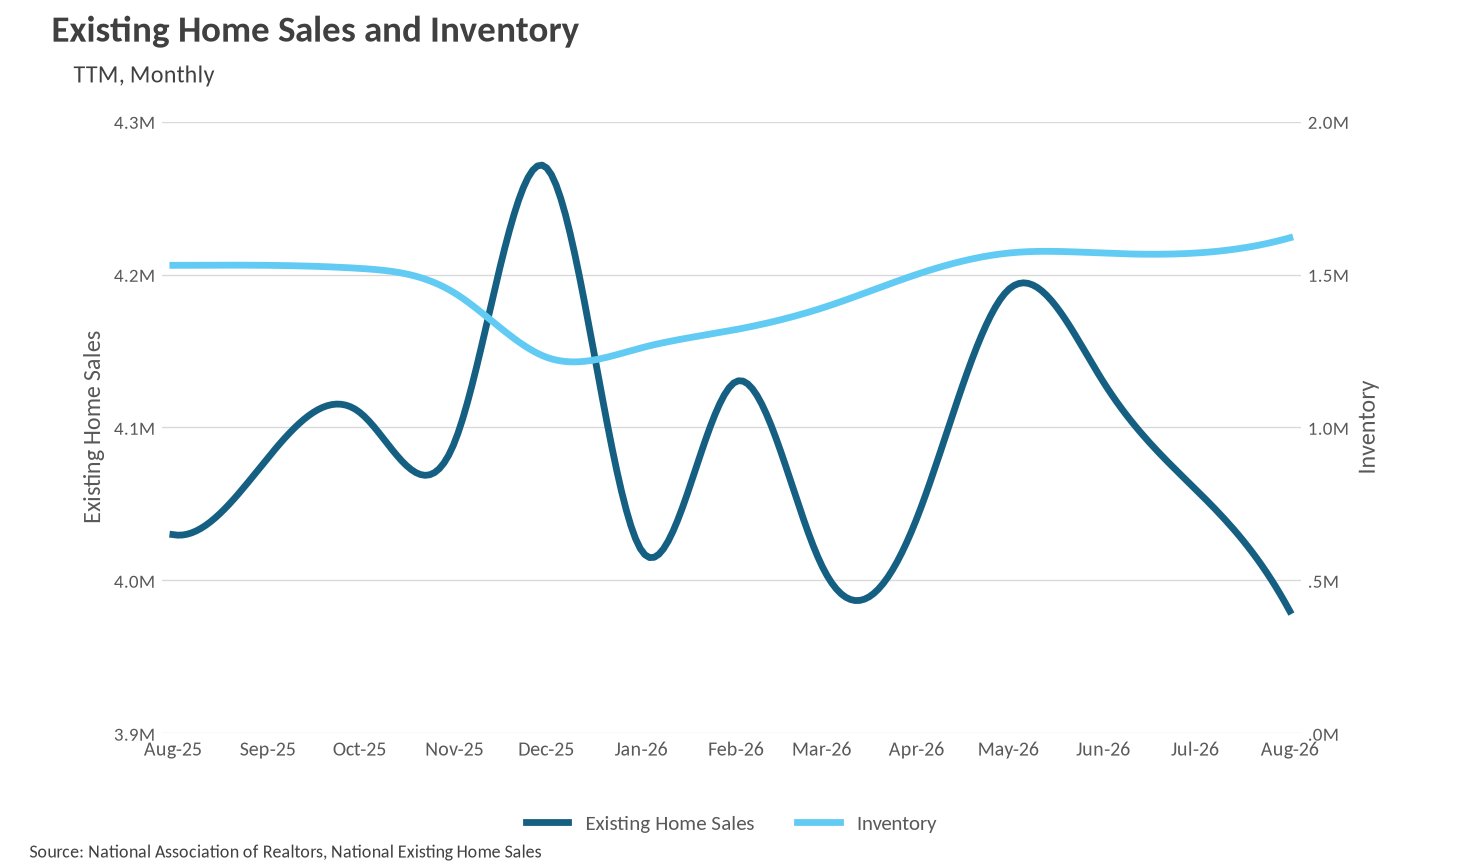
- Inventory pushed higher again in August, reaching 1,620,000 homes for sale, the highest level we have seen in this cycle and nearly 6% above last year.
- Existing home sales fell to 3,980,000, the softest reading in over a year, as mortgage rates climbed to 6.69% in August and 6.71% in September.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.
The spring rally has given way to a summer cooldown
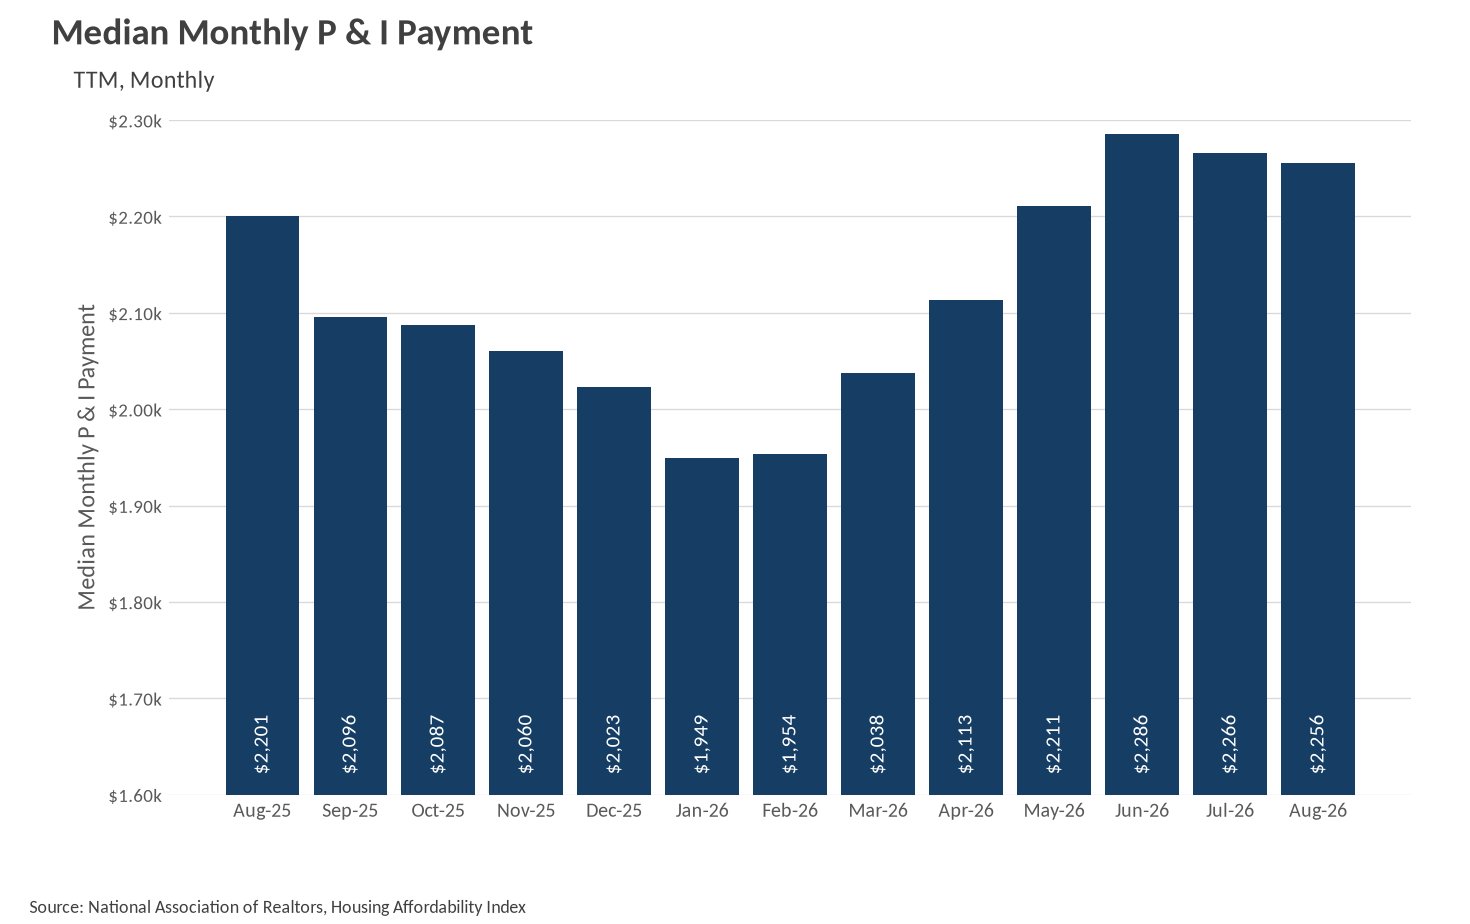
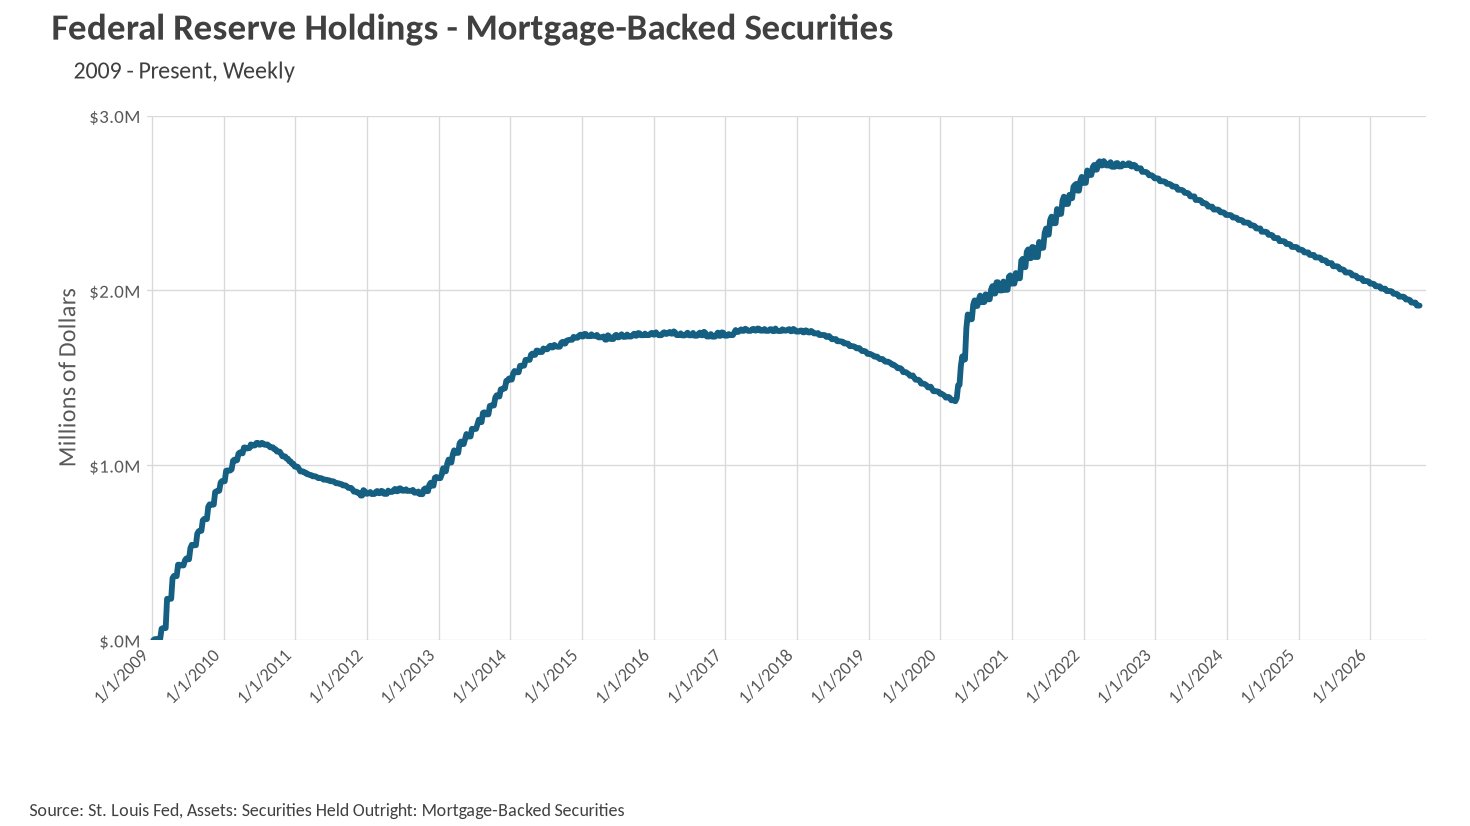
After five straight months of gains carried the median sale price to $442,800 in June, prices have now declined in each of the past two months. In August, the median home sold for $429,100, a 1.67% month-over-month decline from July's $436,400 and a 3.09% pullback from the June peak. The one bright spot is that prices are still running 1.59% above the $422,400 median we saw in August of last year, so the year-over-year comparison remains positive even as the seasonal momentum fades. The affordability story, however, has turned decisively less friendly. Mortgage rates jumped to 6.69% in August and edged up again to 6.71% in September, the highest readings in this entire data series and a full 71 basis points above the 6.00% low we saw back in March. The median monthly principal and interest payment now sits at $2,256, which is 2.50% higher than the $2,201 buyers were paying a year ago and more than $300 above the $1,949 January low. In other words, the affordability cushion that lower rates provided at the start of the year has now been completely erased. It is also worth noting that the Federal Reserve's mortgage-backed securities holdings have continued to run off, declining from roughly $2.05 trillion at the end of last year to about $1.91 trillion in September, which removes a meaningful source of demand for mortgage debt and helps explain why rates have been drifting higher even as the broader market cools.
Inventory keeps building, and that is the real story this month
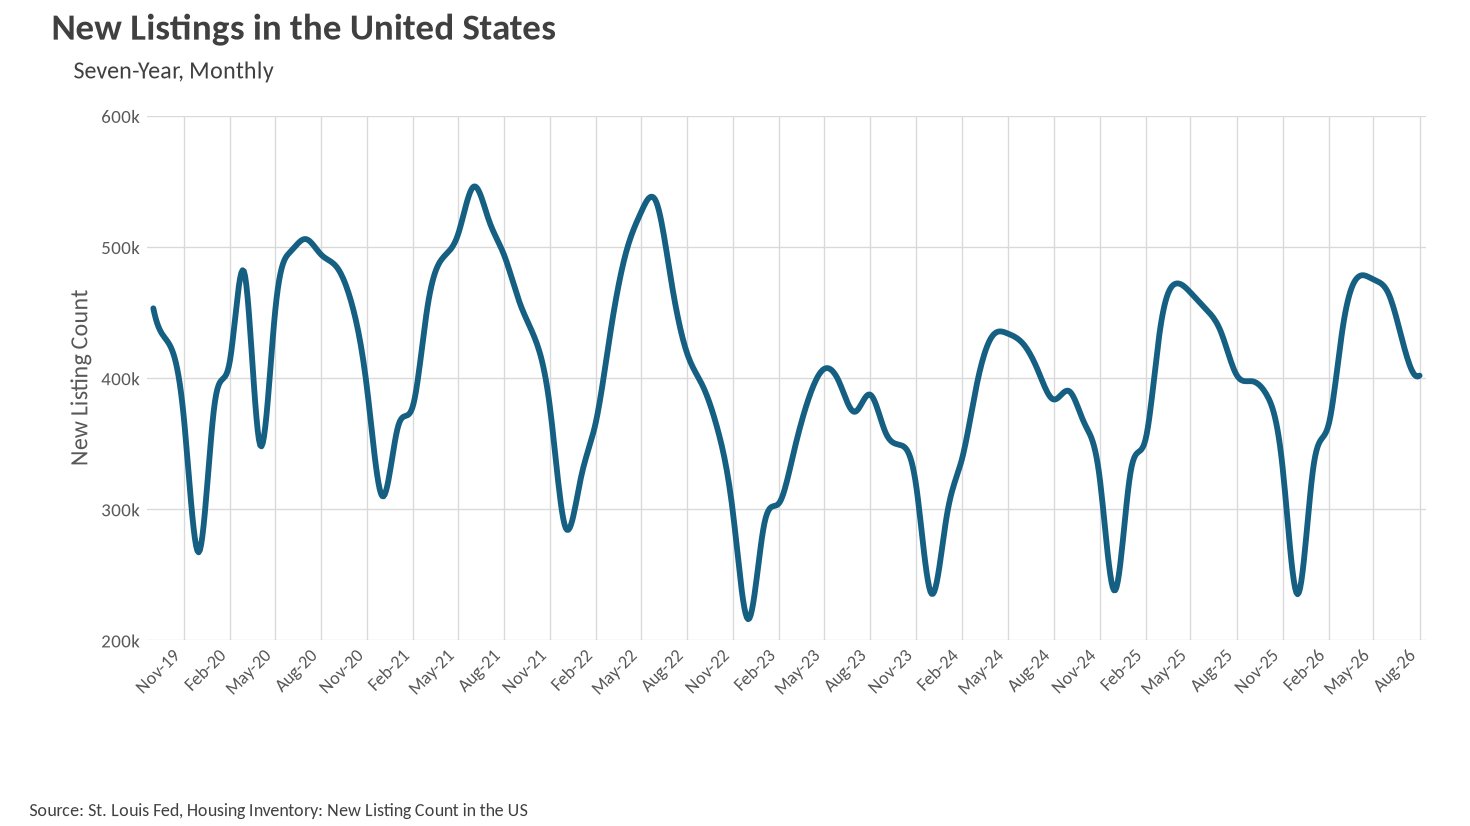
Inventory did not plateau after all. After holding flat at 1,570,000 homes for three consecutive months from May through July, inventory jumped to 1,620,000 in August, a 3.18% month-over-month increase and a 5.88% gain over the 1,530,000 homes available at this time last year. That is the highest inventory level anywhere in this data series, and it represents a 31.7% increase from the December low of 1,230,000. What makes this build particularly notable is that it is not being driven by a flood of new supply. New listings actually fell to 401,760 in August, down 5.18% from July's 423,732 and essentially flat compared to the 402,276 new listings we saw in August of last year. So sellers are not listing more aggressively than they were a year ago. Instead, inventory is accumulating because homes are not clearing at the pace they once did. That distinction matters, because supply that builds from weak absorption tends to be stickier and puts more direct pressure on pricing than supply that builds from a surge of eager sellers.
Existing home sales have slipped below last year's pace
Existing home sales came in at 3,980,000 in August, a 1.97% month-over-month decline from July's 4,060,000 and a 1.24% drop from the 4,030,000 pace we saw in August of last year. This is the weakest sales figure in the data we have, and it marks a clear reversal from the spring, when sales were running above the prior year and reached 4,190,000 in May. The culprit is not hard to identify. Buyers who were enjoying sub-$2,000 monthly payments in January are now looking at $2,256, and mortgage rates that started the year at 6.16% are now sitting at 6.71%. When financing costs move that much in nine months, the marginal buyer simply steps out of the market, and that is exactly what the sales data is showing. Three consecutive months of declining sales, combined with inventory pushing to new highs, tells us that the balance of the market has shifted in a way it had not through the first half of the year. The question now is whether rates stabilize and let buyers re-engage this fall, or whether we continue to see demand erode into the winter.
Buyers are gaining leverage for the first time in a while
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of HSI is considered buyers’ markets.
At the national level, the numbers point clearly toward a buyers' market. With 1,620,000 homes for sale in August against an annualized sales pace of 3,980,000, the implied months of supply works out to roughly 4.9 months, comfortably above the three-month threshold that separates balanced markets from buyers' markets. A year ago, that same calculation produced about 4.6 months, so supply has loosened meaningfully over the past twelve months. Every component of the equation is currently moving in buyers' favor: inventory is at a cycle high and rising, sales are falling on both a monthly and annual basis, and median prices have declined for two straight months. The obvious catch is affordability. Buyers may have more negotiating room and more homes to choose from than at any point in recent memory, but with rates at 6.71% and monthly payments up more than $300 since January, the cost of taking advantage of that leverage has risen sharply. Sellers, for their part, should expect longer marketing times and more price sensitivity than they saw this spring. As always, real estate is a highly localized asset, which is why you should check out what's going on in your local market below in the Local Lowdown!
Big Story Data
The Local Lowdown
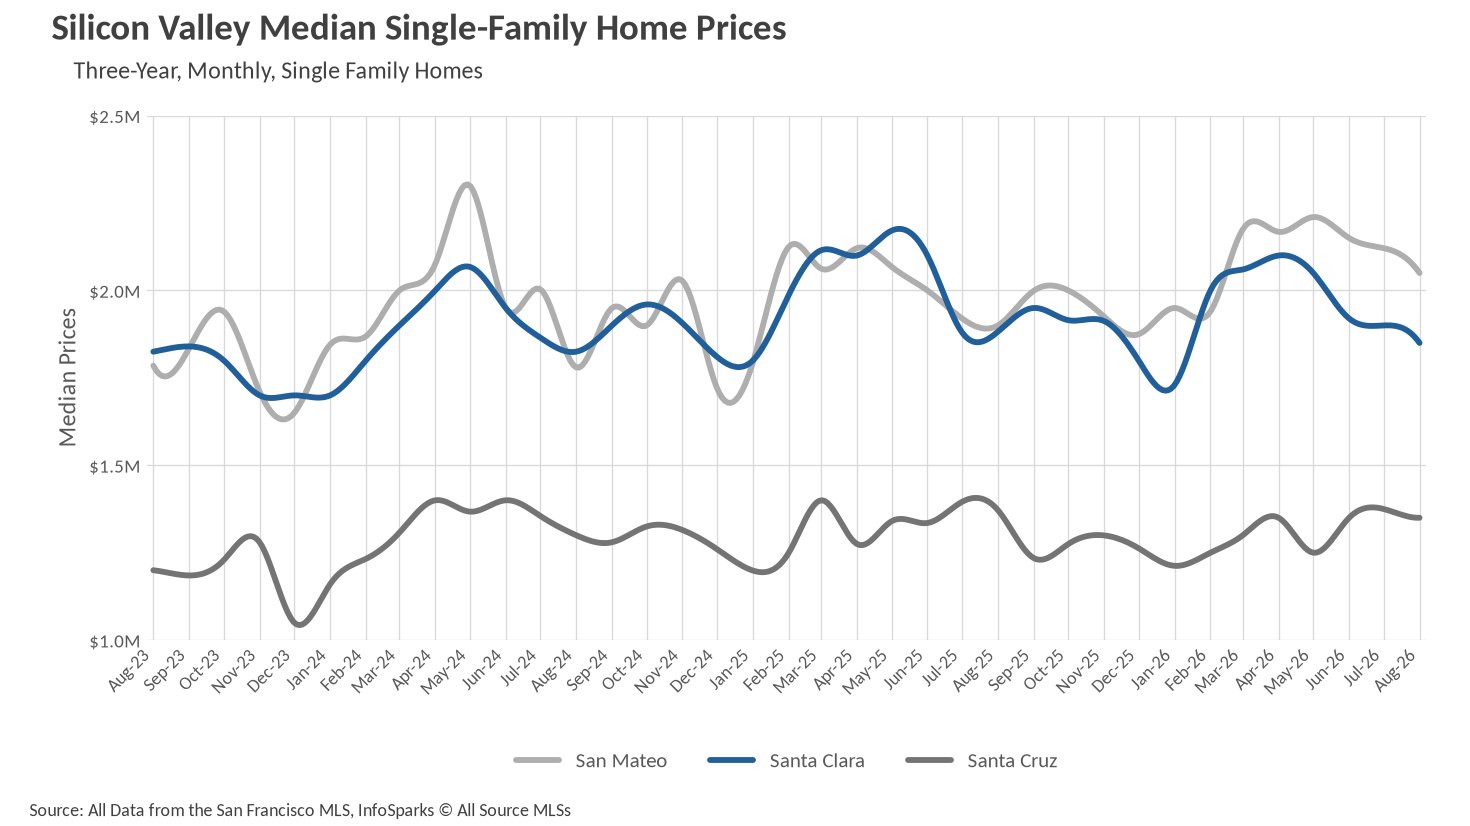
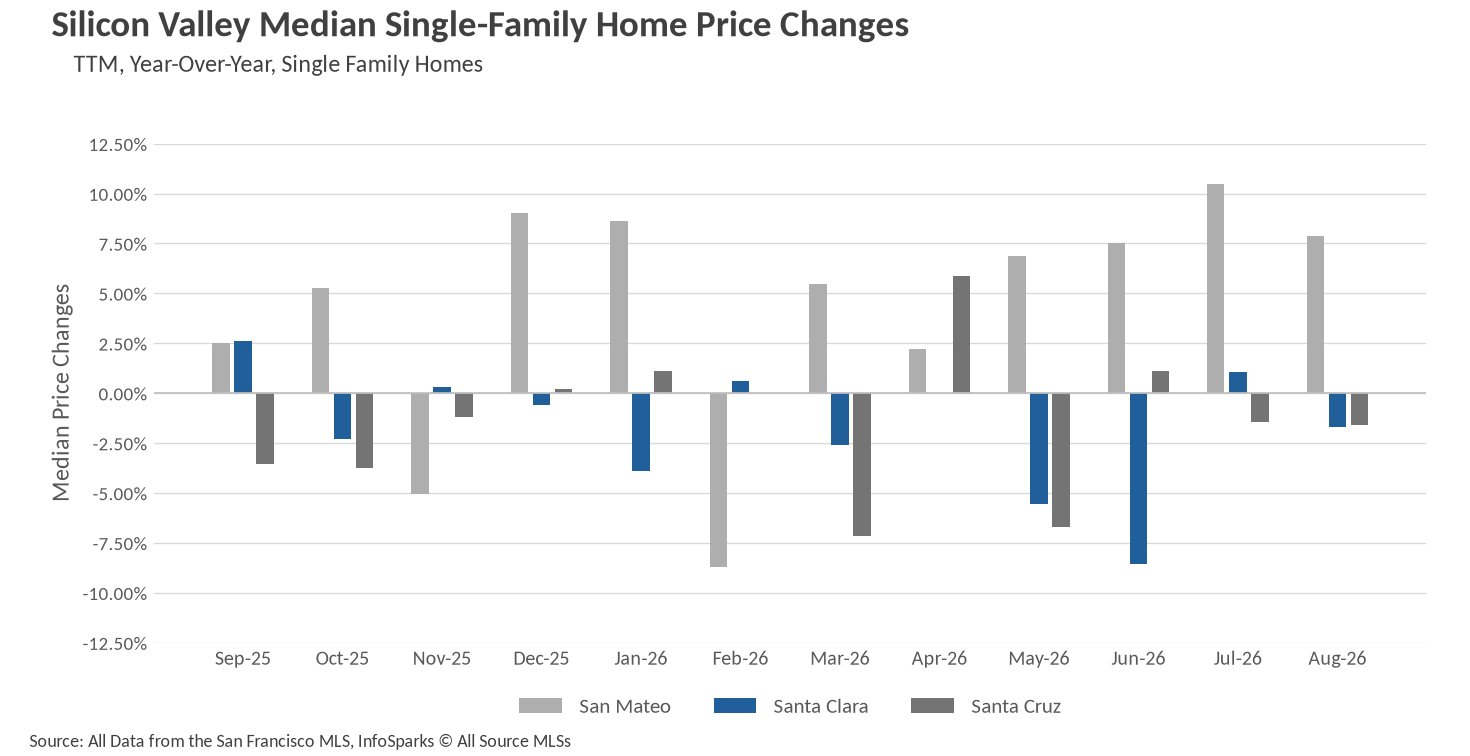
- Single-family median prices diverged again in August, with San Mateo County up nearly 8% year over year while Santa Clara and Santa Cruz Counties slipped modestly below last August's levels.
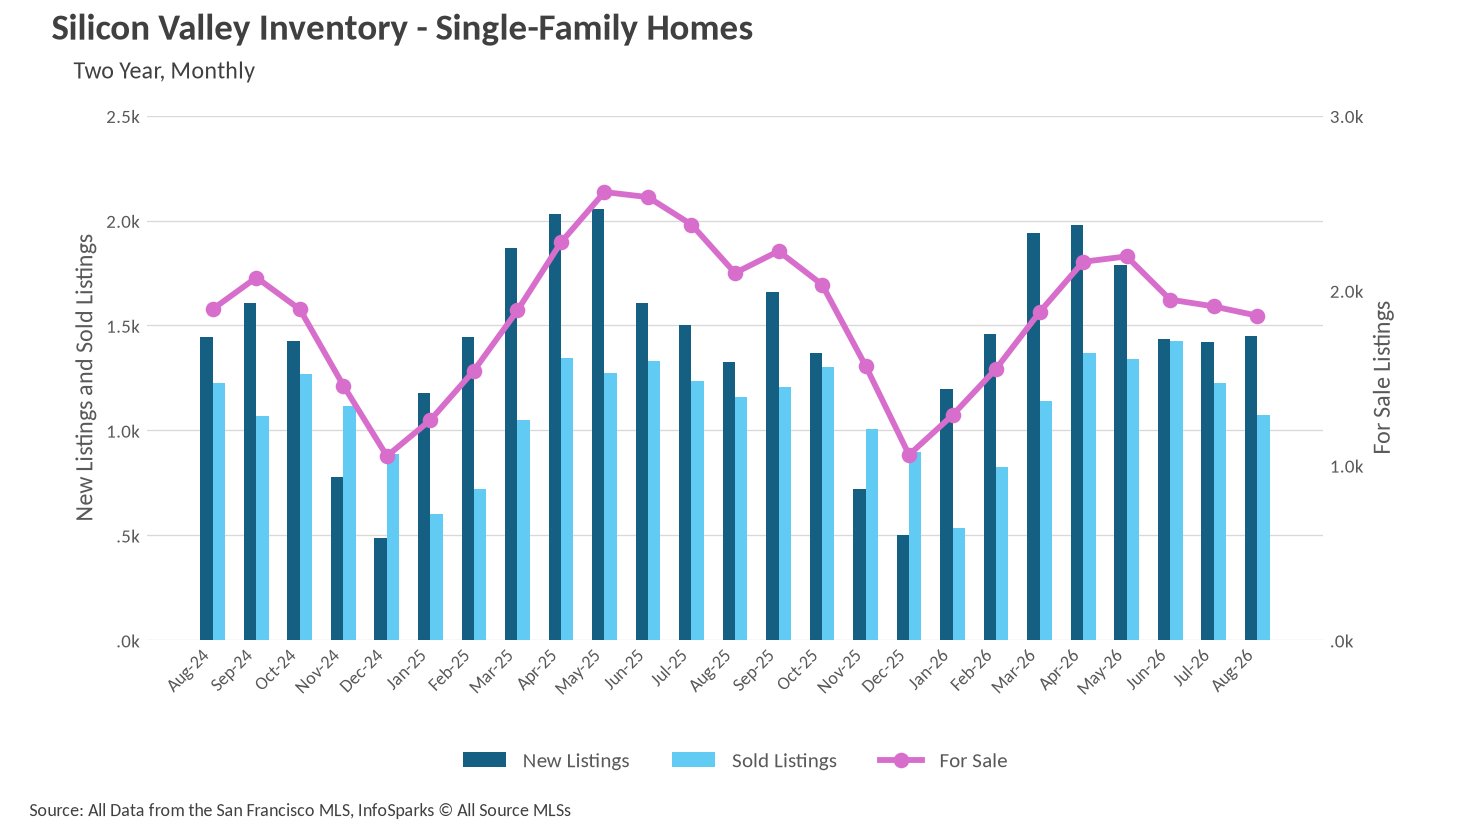
- Inventory tightened meaningfully, with 1,856 single-family homes for sale across the region, down 11.62% year over year, and condo listings falling 13.27% to 765.
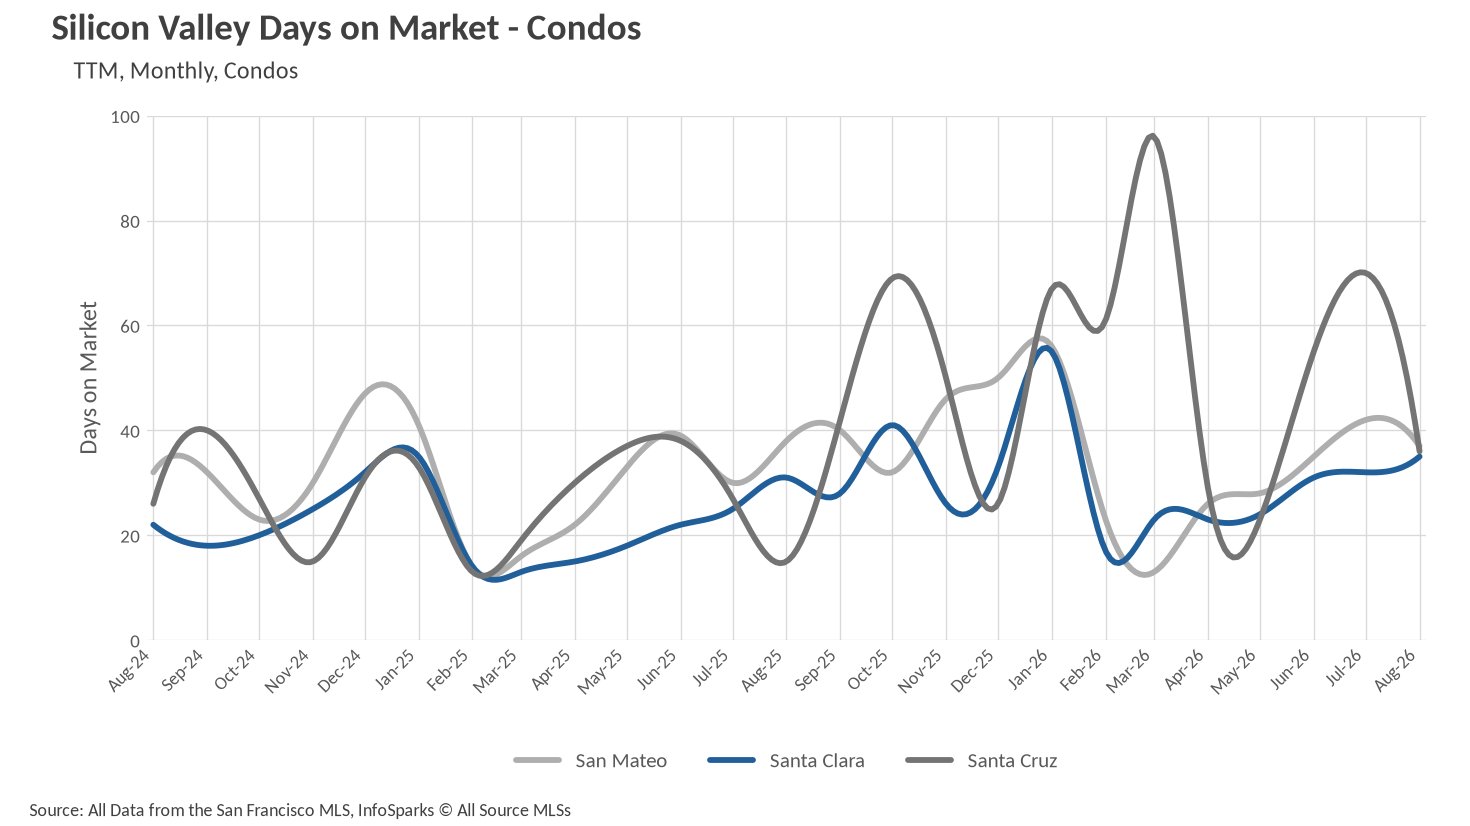
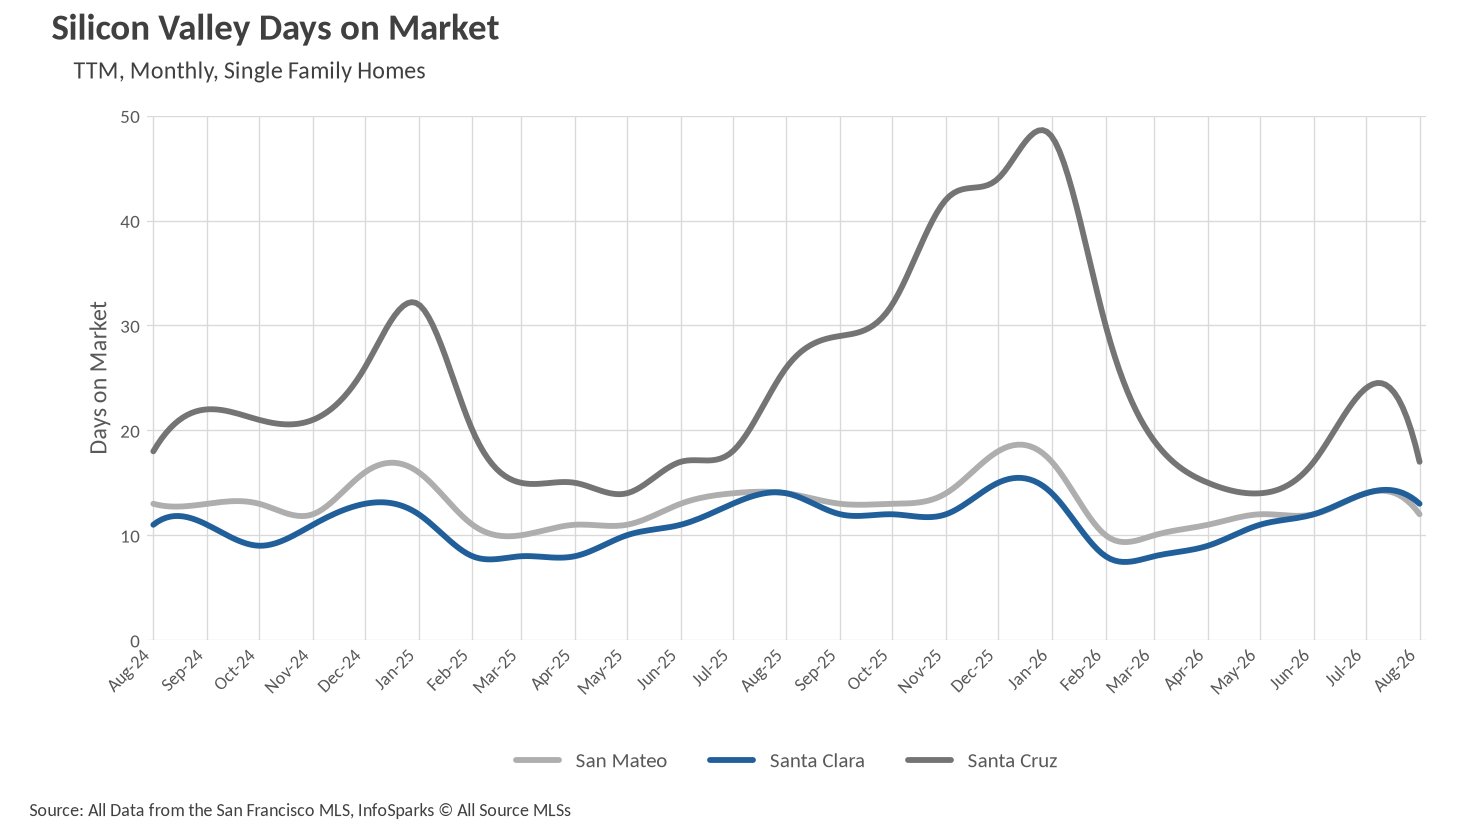
- Single-family homes continue to move in roughly two weeks, and Santa Cruz County saw the sharpest speed-up, selling in 17 days versus 26 a year ago.
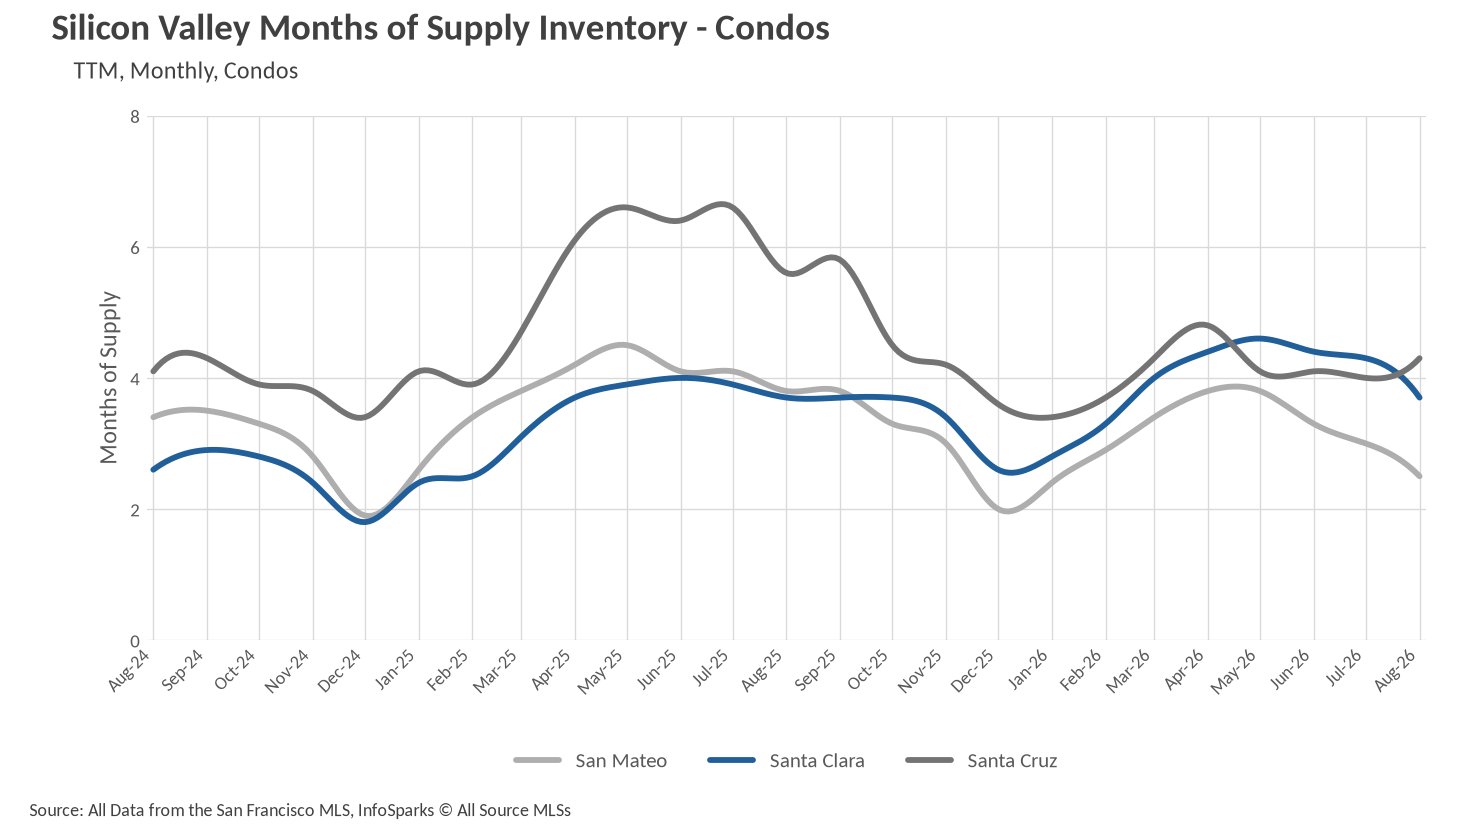
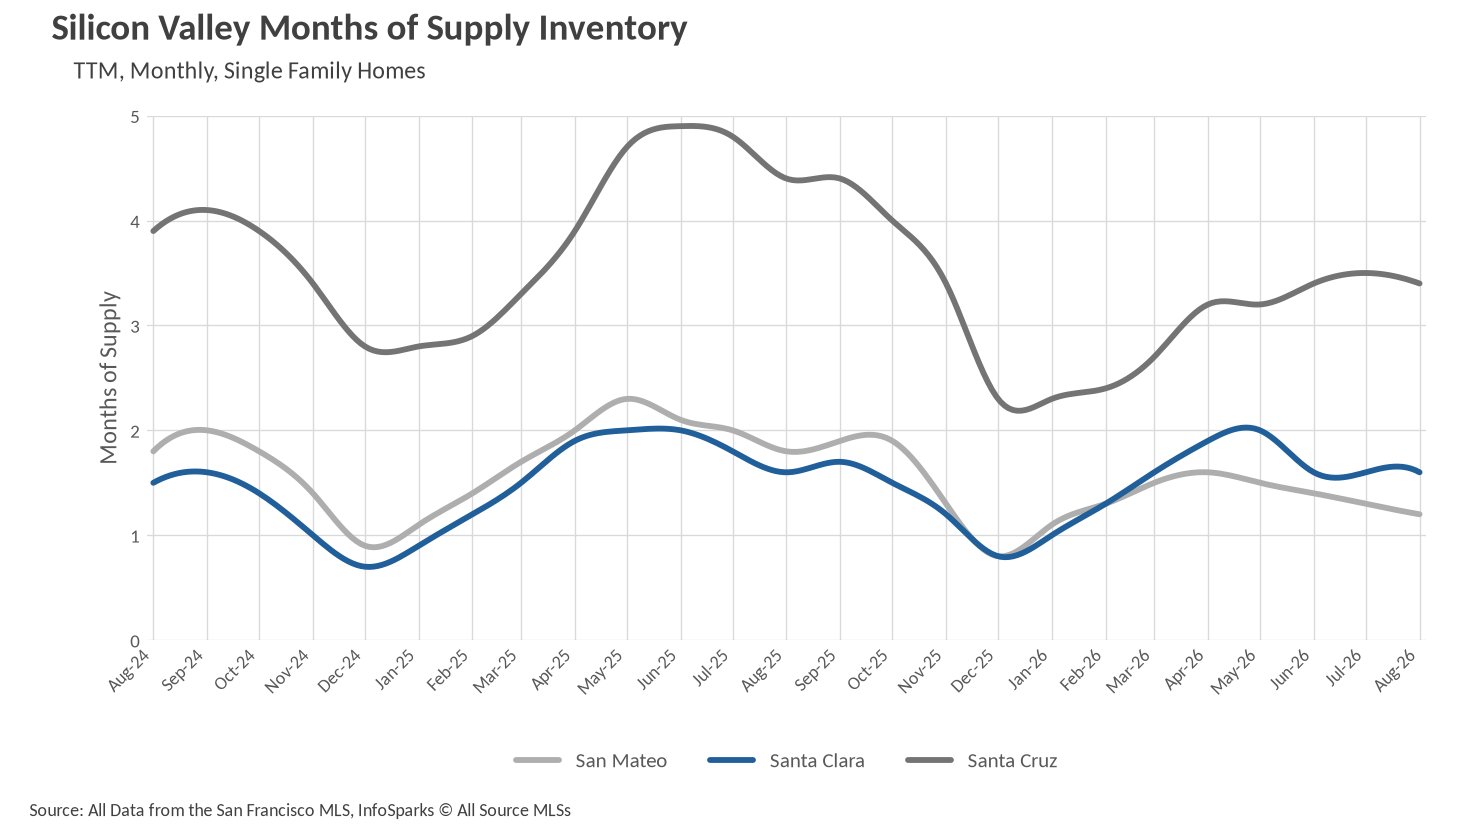
- Months of supply fell across most segments, with San Mateo County condos dropping into seller's market territory at 2.5 months.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
San Mateo holds the high ground as its neighbors ease back
August brought the usual late-summer cooling to Silicon Valley pricing, but the year-over-year story remains split. San Mateo County continues to lead, with the median single-family home selling for $2,050,000, an increase of 7.89% over last August's $1,900,000. That figure is off the $2,210,000 peak set in May and down 3.35% from July, which is consistent with the seasonal fade we typically see as summer winds down, but the county has now spent six straight months above the $1.9 million mark.
Santa Clara County, by contrast, posted a median of $1,850,000, a 1.70% decline from last August and a third consecutive monthly step down from the $2,100,000 April reading. Santa Cruz County landed at $1,350,000, down 1.60% year over year and 1.82% from July, though still comfortably inside the narrow $1.2 million to $1.4 million band it has occupied all year.
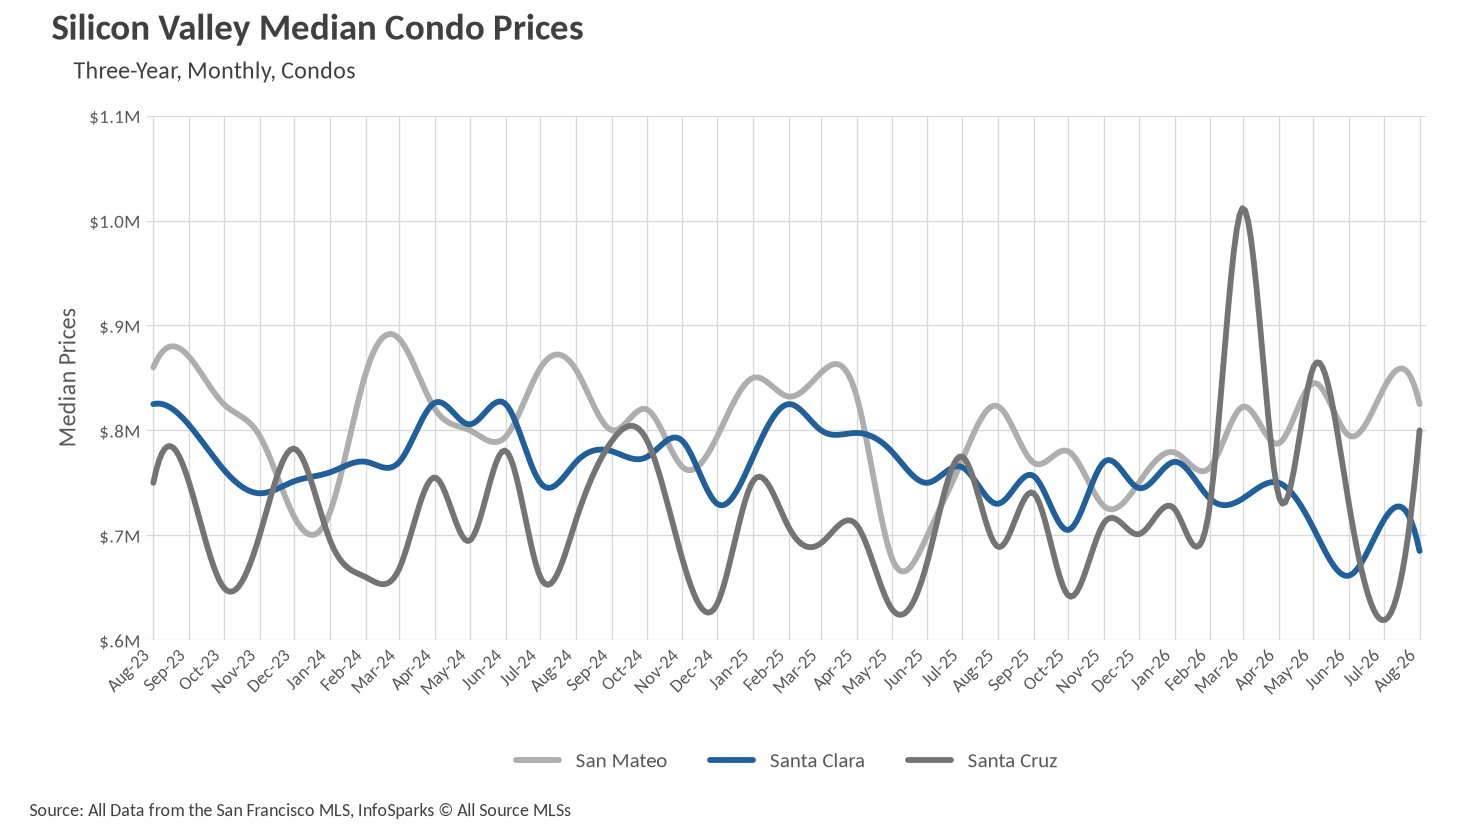
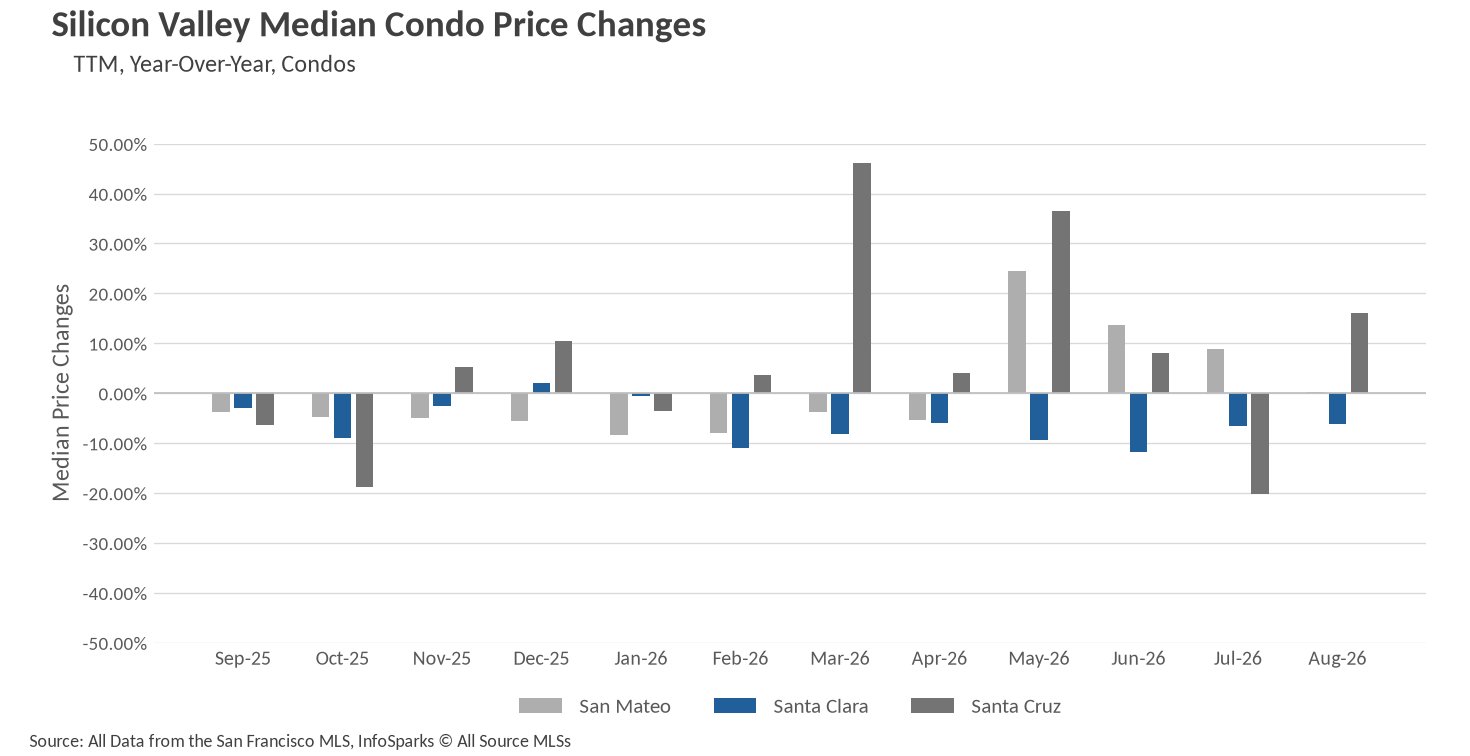
The condo picture is noisier. San Mateo County condos were essentially flat year over year at $825,000, up just 0.24%, while Santa Clara County condos slid 6.16% to $685,000, continuing a soft stretch that has seen that market trade below $720,000 in four of the last five months. Santa Cruz County condos jumped to $800,000, up 16.11% year over year, but readers should treat that number with caution given the thin transaction counts and the wild swings this segment has shown in 2026, from $619,000 in July to $1,012,000 back in March.
Supply tightens even as sellers step back into the market
Inventory moved in a direction sellers like this month. There were 1,856 single-family homes for sale across Silicon Valley in August, down 2.78% from July's 1,909 and down 11.62% from the 2,100 available last August. That marks the fourth consecutive monthly decline from the May peak of 2,195, and it means available supply is thinner than it was at the same point in each of the two prior years.
Interestingly, this tightening is not coming from a lack of sellers. New single-family listings actually rose to 1,451, up 9.51% year over year and up slightly from July, suggesting homeowners are still willing to test the market. The squeeze is coming from the demand side being a bit quieter: 1,073 single-family homes sold in August, down 7.58% from last August and off 12.48% from July's 1,226. In other words, fewer closings and fewer homes on the shelf at the same time, a combination that keeps the market feeling tight without feeling frantic.
Condos tightened even faster. Just 765 units were listed for sale, an 11.76% drop from July and a 13.27% decline from last August's 882. New condo listings edged down 1.75% year over year to 336, and sales were essentially steady at 236, down 1.26%. After a year in which condo supply consistently ran near or above 900 units, August's reading is the lowest since December.
Two weeks or less across the single-family market
Speed remains the defining characteristic of the single-family segment. San Mateo County homes sold in an average of 12 days, a 14.29% improvement over the 14 days recorded last August and two days faster than July. Santa Clara County came in at 13 days, down 7.14% year over year, and the two counties have now traded places within a day or two of each other for most of 2026.
The most dramatic improvement was in Santa Cruz County, where homes averaged 17 days, a 34.62% reduction from last August's 26 days and a sharp acceleration from July's 24. That is a meaningful turnaround for a market that saw days on market balloon into the 40s over the winter.
Condos continue to require more patience. San Mateo County condos averaged 37 days, effectively unchanged from last August's 38 and five days quicker than July. Santa Clara County condos took 35 days, a 12.90% increase over last year and the slowest reading in that county since the January spike. Santa Cruz County condos averaged 36 days, which looks alarming next to last August's unusually quick 15 days, but it is actually a substantial improvement from the 70 days logged in July and the 96 days recorded in March.
Silicon Valley's sellers keep the upper hand heading into fall
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
By that measure, the single-family market across Silicon Valley remains firmly in sellers' hands. San Mateo County sits at just 1.2 months of supply, down 33.33% from the 1.8 months available last August and the lowest reading since December. Santa Clara County holds at 1.6 months, unchanged year over year and steady for three straight months, which is still deep seller's territory. Santa Cruz County, at 3.4 months, is the region's most balanced single-family market, though its supply has fallen 22.73% from last August's 4.4 months and it has hovered between 3.2 and 3.5 months since spring.
Condos tell a more nuanced story, and the headline this month is San Mateo County crossing the line. At 2.5 months of supply, down 34.21% from 3.8 months a year ago, San Mateo condos now qualify as a seller's market for the first time since late last year. Santa Clara County condos sit at 3.7 months, flat year over year but down from 4.3 in July, putting them just on the buyers' side of balanced. Santa Cruz County condos remain the most buyer-friendly segment in the region at 4.3 months, although that is a 23.21% improvement for sellers compared with last August's 5.6 months.
The takeaway heading into fall: single-family buyers should still expect to compete, move quickly, and come prepared, while condo shoppers in Santa Clara and Santa Cruz Counties retain genuine negotiating room. Sellers in San Mateo County, in either property type, are operating from the strongest position in the region.
Local Lowdown Data